Sanctions travel through financial networks, commodity markets, supply chains and investment decisions. For emerging markets, the central question is not whether a country appears on a list, but how exposure moves through institutions and contracts.
At a glance
- Sanctions can affect non-targeted economies through banks, payment routes, commodity prices, shipping, insurance and investment reallocation.
- The same measure can hurt an energy importer, benefit a commodity exporter and raise compliance costs for both.
- Sound decisions require entity-level exposure mapping and scenario analysis, not country labels or headline-driven exits.
A network shock, not a country event
Economic sanctions are used in many forms: asset freezes, financial restrictions, export controls, import bans, service prohibitions and limits on particular transactions. The Global Sanctions Data Base documents hundreds of bilateral, plurilateral and multilateral cases since 1950. [1] Their frequency does not make their effects uniform. Design, enforcement, coalition breadth, target adaptation and third-country responses all matter.
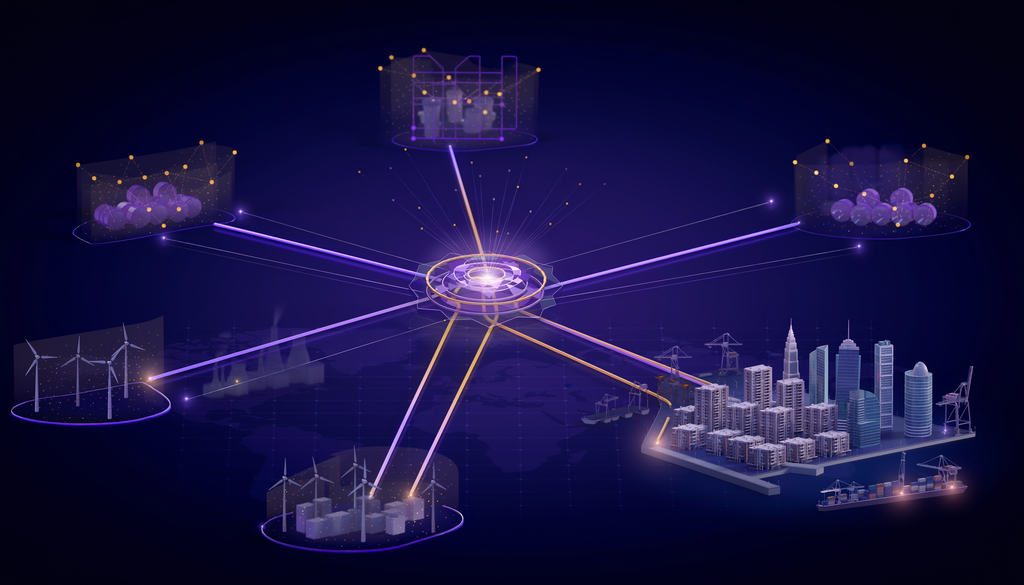
For an emerging market, formal non-participation does not create insulation. A local bank may rely on a foreign correspondent. An importer may buy fuel priced from a disrupted benchmark. A manufacturer may use a distributor whose beneficial owner is designated. A fund may hold an apparently domestic company whose revenues, lenders or suppliers create indirect exposure. Sanctions therefore behave less like a line around one jurisdiction and more like a shock transmitted through a network.
Four transmission channels
1. Payments and counterparty de-risking
Cross-border payments still depend heavily on correspondent banking. The Bank for International Settlements notes that this network has become more concentrated, which increases the importance of a limited number of intermediaries. [6] When a regulator acts against one institution, counterparties may reduce exposure beyond the narrow legal requirement because they cannot assess the risk quickly or because the relationship is too small to justify additional due diligence.
The June 2025 action against CIBanco, Intercam Banco and Vector Casa de Bolsa shows the mechanism. The United States Financial Crimes Enforcement Network identified the three Mexico-based institutions as primary money-laundering concerns in connection with illicit opioid trafficking and issued orders prohibiting certain transmittals of funds involving them. [4] These were regulator allegations and targeted transfer restrictions, not a general freeze on all Mexican financial activity. Mexico requested supporting evidence, while the named institutions disputed or did not accept aspects of the allegations. [8] The analytical point is the speed with which an entity-level measure can alter correspondent, trustee and customer relationships.
2. Commodity prices and macroeconomic policy
Sanctions imposed during a conflict often arrive alongside physical disruption, voluntary corporate withdrawal and expectations of future scarcity. Those forces must not be collapsed into a single cause. In April 2022, the World Bank expected energy prices to rise by more than 50 per cent that year and non-energy prices by almost 20 per cent, with especially large increases in commodities for which Russia or Ukraine were important exporters. [3] The report attributed the shock to the war and related disruptions, including trade and financial restrictions.
The effect on emerging markets depended on their starting position. Net importers faced larger fuel and food bills, wider current-account deficits, inflation pressure and harder fiscal choices over subsidies. Some commodity exporters gained revenue, but windfalls could be offset by higher input costs, financing stress or later price reversals. A sanction episode can therefore widen differences within the emerging-market universe rather than create one common outcome.
3. Trade diversion and compliance opacity
Restricted trade rarely disappears in full. It may be replaced, rerouted or repriced. New intermediaries, trans-shipment points and payment arrangements can create business for third countries, while also raising documentation, beneficial-ownership and end-use checks. The result is a difficult combination: some firms see higher volumes at the same time that legal, reputational and settlement risks become harder to observe.
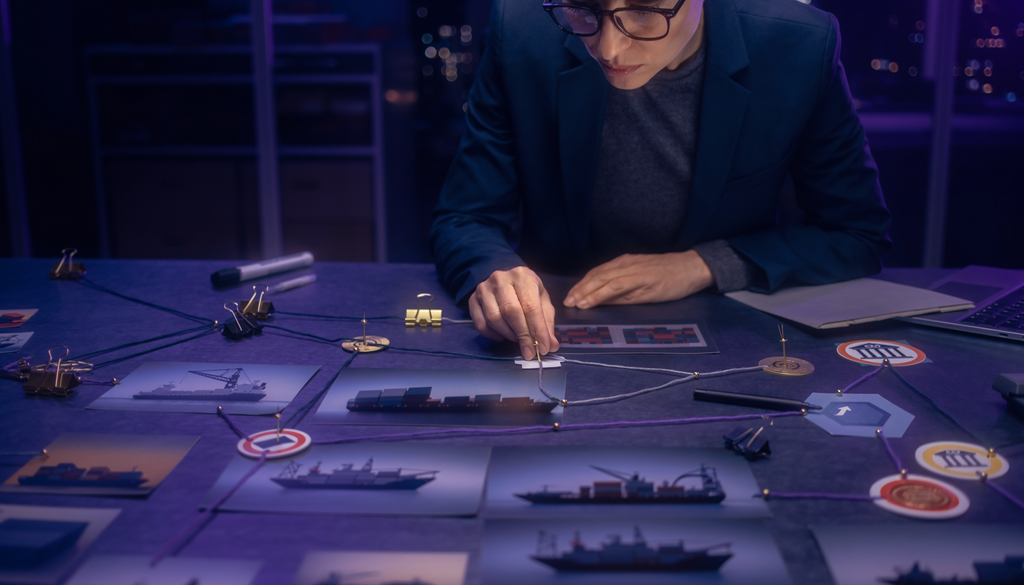
This is why exposure should be mapped at transaction level. The relevant questions include who owns the buyer, who receives the goods, which bank clears the payment, which insurer covers the cargo, which vessel carries it and whether the product contains controlled technology. A country that is not itself sanctioned can still contain a high-risk transaction chain.
4. Investment fragmentation
The IMF’s 2023 analysis found that foreign direct investment was becoming more concentrated among geopolitically aligned countries, particularly in strategic sectors. It also found evidence that some non-aligned economies could receive diverted investment. [2] Such “connector” gains may be real, but they can be fragile if they depend on one corridor, one regulatory interpretation or one geopolitical relationship. Diversion is not the same as durable diversification.
Why institutional capacity changes the outcome
Two countries with similar growth rates can react very differently to the same sanctions shock. Foreign-exchange reserves, currency denomination of debt, domestic capital-market depth, energy dependence, food-import concentration and the credibility of public institutions all shape the adjustment. Larger economies may have more suppliers and funding routes. Smaller economies may face a sharper loss of access when one bank or shipping service exits.
Alternative payment systems and local-currency settlement can reduce reliance on a single channel, but they do not erase sanctions obligations or counterparty risk. The legal question follows the institution, jurisdiction, entity and transaction. Technology changes the route; it does not remove the need for governance.
A decision framework for institutions and investors
Map legal exposure separately from market exposure
Legal exposure asks whether a person, entity, product, service or payment is prohibited. Market exposure asks how restrictions could affect prices, liquidity, settlement, demand or policy even when the transaction remains lawful. Combining the two produces false certainty.
Build the counterparty graph
Go beyond immediate names. Identify beneficial owners, parent companies, banks, correspondent banks, insurers, freight providers, end users and material suppliers. Update the map when ownership or routing changes.
Stress-test at least three paths
A useful baseline covers the current measures. An escalation case tests wider designations, tighter enforcement or loss of a payment route. An adaptation case tests trade diversion, alternative suppliers and policy support. Each case should specify indicators that would confirm or weaken it.
Use a documented compliance system
The United States Treasury’s Framework for OFAC Compliance Commitments identifies management commitment, risk assessment, internal controls, testing and training as core elements of a sanctions-compliance programme. [7] Institutions subject to other regimes should adapt the same governance logic to the laws that apply to them and seek qualified legal advice for specific transactions.
Takeaway
Sanctions are targeted legal instruments, but their economic effects are distributed by networks. Emerging markets can absorb shocks through finance, commodities, trade routes and investment even when they are not the formal target. Some will also receive diverted trade or capital.
The strategic task is to identify which channel matters, separate legal prohibition from economic spillover and watch the indicators that could change the assessment. For decision-makers, disciplined exposure mapping is more useful than either complacency or alarm.
Sources
- Felbermayr et al., The Global Sanctions Data Base. European Economic Review, 2020.
- International Monetary Fund, Geoeconomic Fragmentation and Foreign Direct Investment. World Economic Outlook, April 2023, Chapter 4.
- World Bank, Commodity Markets Outlook: The Impact of the War in Ukraine on Commodity Markets. April 2022.
- Financial Crimes Enforcement Network, Orders concerning three Mexican financial institutions. 25 June 2025.
- Federal Register, Extension of the effective date for the June 2025 FinCEN orders. 11 July 2025.
- Bank for International Settlements, Monitoring cross-border payments. CPMI monitoring resources.
- United States Department of the Treasury, A Framework for OFAC Compliance Commitments. 2 May 2019.
- Reuters, US bans certain deals with two Mexican banks and a broker. 25 June 2025; used for the institutions’ and Mexican authorities’ responses.